What happened when the "Taxi King" lost his crown? Check out this case study in disruption and debt
|
|
| For this article, let’s talk about the “Illusion of Permanence.” Ready? Keep reading below to know more. What happened when the "Taxi King" lost his crown? Check out this case study in disruption and debt. In the world of business, empires rarely collapse with a dramatic BANG. They usually erode quietly, almost politely, until one day, the numbers tell a story no narrative can defend. For seasoned investors, that moment is familiar. It’s the precise point when a once “untouchable” asset reveals itself to be anything but. … and as Professor Joel Litman, Chairman and CEO of Valens Research and Chief Investment Officer of Altimetry Financial Research, has emphasized, those moments aren’t random. They’re actually predictable if you know where to look. The Illusion of Permanence In examining one of the most dramatic value collapses in modern urban infrastructure, Professor Litman pointed to the rise and fall of the taxi medallion empire built by Gene Freidman.
Freidman’s story begins not with ambition, but with inheritance. After immigrating to the U.S., his father built a modest taxi operation in New York City, eventually growing it into a fleet business. When his father fell ill in the mid-1990s, Freidman stepped in, inheriting not just a business but also an opportunity. What followed was a masterclass in exploiting structural scarcity. Taxi medallions—government-issued permits required to operate cabs in New York—were artificially limited in supply. As demand for taxi services grew through the late 1990s and early 2000s, so did the value of these medallions. Freidman saw what many missed: Scarcity plus rising demand equals pricing power . … and he leaned in aggressively. Freidman’s strategy was straightforward, and for a time, brilliantly effective. He accumulated medallions—hundreds, then nearly a thousand—using leverage to accelerate his expansion. At peak valuations, individual medallions surpassed USD 1 million. His portfolio crossed the billion-dollar mark. From a traditional lens, this looked like dominance… but as Professor Litman explained, this is where investors often get it wrong. High asset values DO NOT necessarily reflect durable returns. In fact, they can mask fragility. Freidman’s empire was built on two assumptions:
Both assumptions would soon be tested—and broken. The Disruption No One Could Ignore By the early 2010s, a new model began to emerge. Companies like Uber Technologies and Lyft redefined urban transportation.
They didn’t rely on scarce permits but on software, network effects, and user experience (UX). For customers, the shift was immediate: cleaner cars, faster pickups, and transparent pricing. For medallion owners, it was existential. As Professor Litman noted, the market didn’t collapse because taxis stopped existing; it collapsed because the economic advantage behind medallions disappeared. Once that advantage eroded, the leverage that once amplified returns began to accelerate losses. By the mid-2010s, medallion prices were in freefall. Auctions that once commanded seven figures struggled to attract bids at a fraction of that value. The result? Freidman’s empire, heavily financed by debt, couldn’t withstand the shift. The New “Taxi King” While Freidman’s model unraveled, a new kind of dominance was quietly taking shape… Uber Technologies didn’t just replace taxis; it also reimagined the business entirely. As Professor Litman highlighted, Uber’s strength lies not in owning physical assets, but in orchestrating a platform:
This asset-light, platform-based model has proven far more resilient. By the mid-2020s, Uber had achieved something many doubted: sustained profitability . Its Uniform return on assets surged well above corporate averages, reflecting true economic strength and not just accounting optics. What else? Crucially, Uber demonstrated adaptability. When its early push into autonomous driving lagged behind competitors like Alphabet-owned Waymo, Uber pivoted, eventually partnering rather than competing head-on. According to Professor Litman, that decision reflects a fundamental difference between the old and new “Taxi Kings”: Freidman bet on permanence. Uber bets on evolution. — You see, markets continue to reward adaptability and punish rigidity. The lesson here isn’t simply about taxis or ride-hailing; it’s also about how quickly competitive advantages can disappear, and how dangerous it is to assume they won’t. For investors, the implications are clear:
What makes the fall of the taxi medallion empire so instructive isn’t just its scale but also how obvious it looks in hindsight. That’s the trap. As Professor Litman often underscores, the biggest risks in investing aren’t the ones no one sees. They’re the ones everyone sees but chooses to ignore . For a while, the numbers still look good. The narrative still holds. The empire still stands. Then, it doesn’t. … and when that happens, it’ll be too late. Hope you’ve found this week’s insights interesting and helpful. Stay tuned for next Wednesday’s The Independent Investor! This father just wanted to ease his son’s pain, but he ended up creating a product used by many across the globe. Learn more about the hot-tub lesson every investor should learn in next week’s article! |


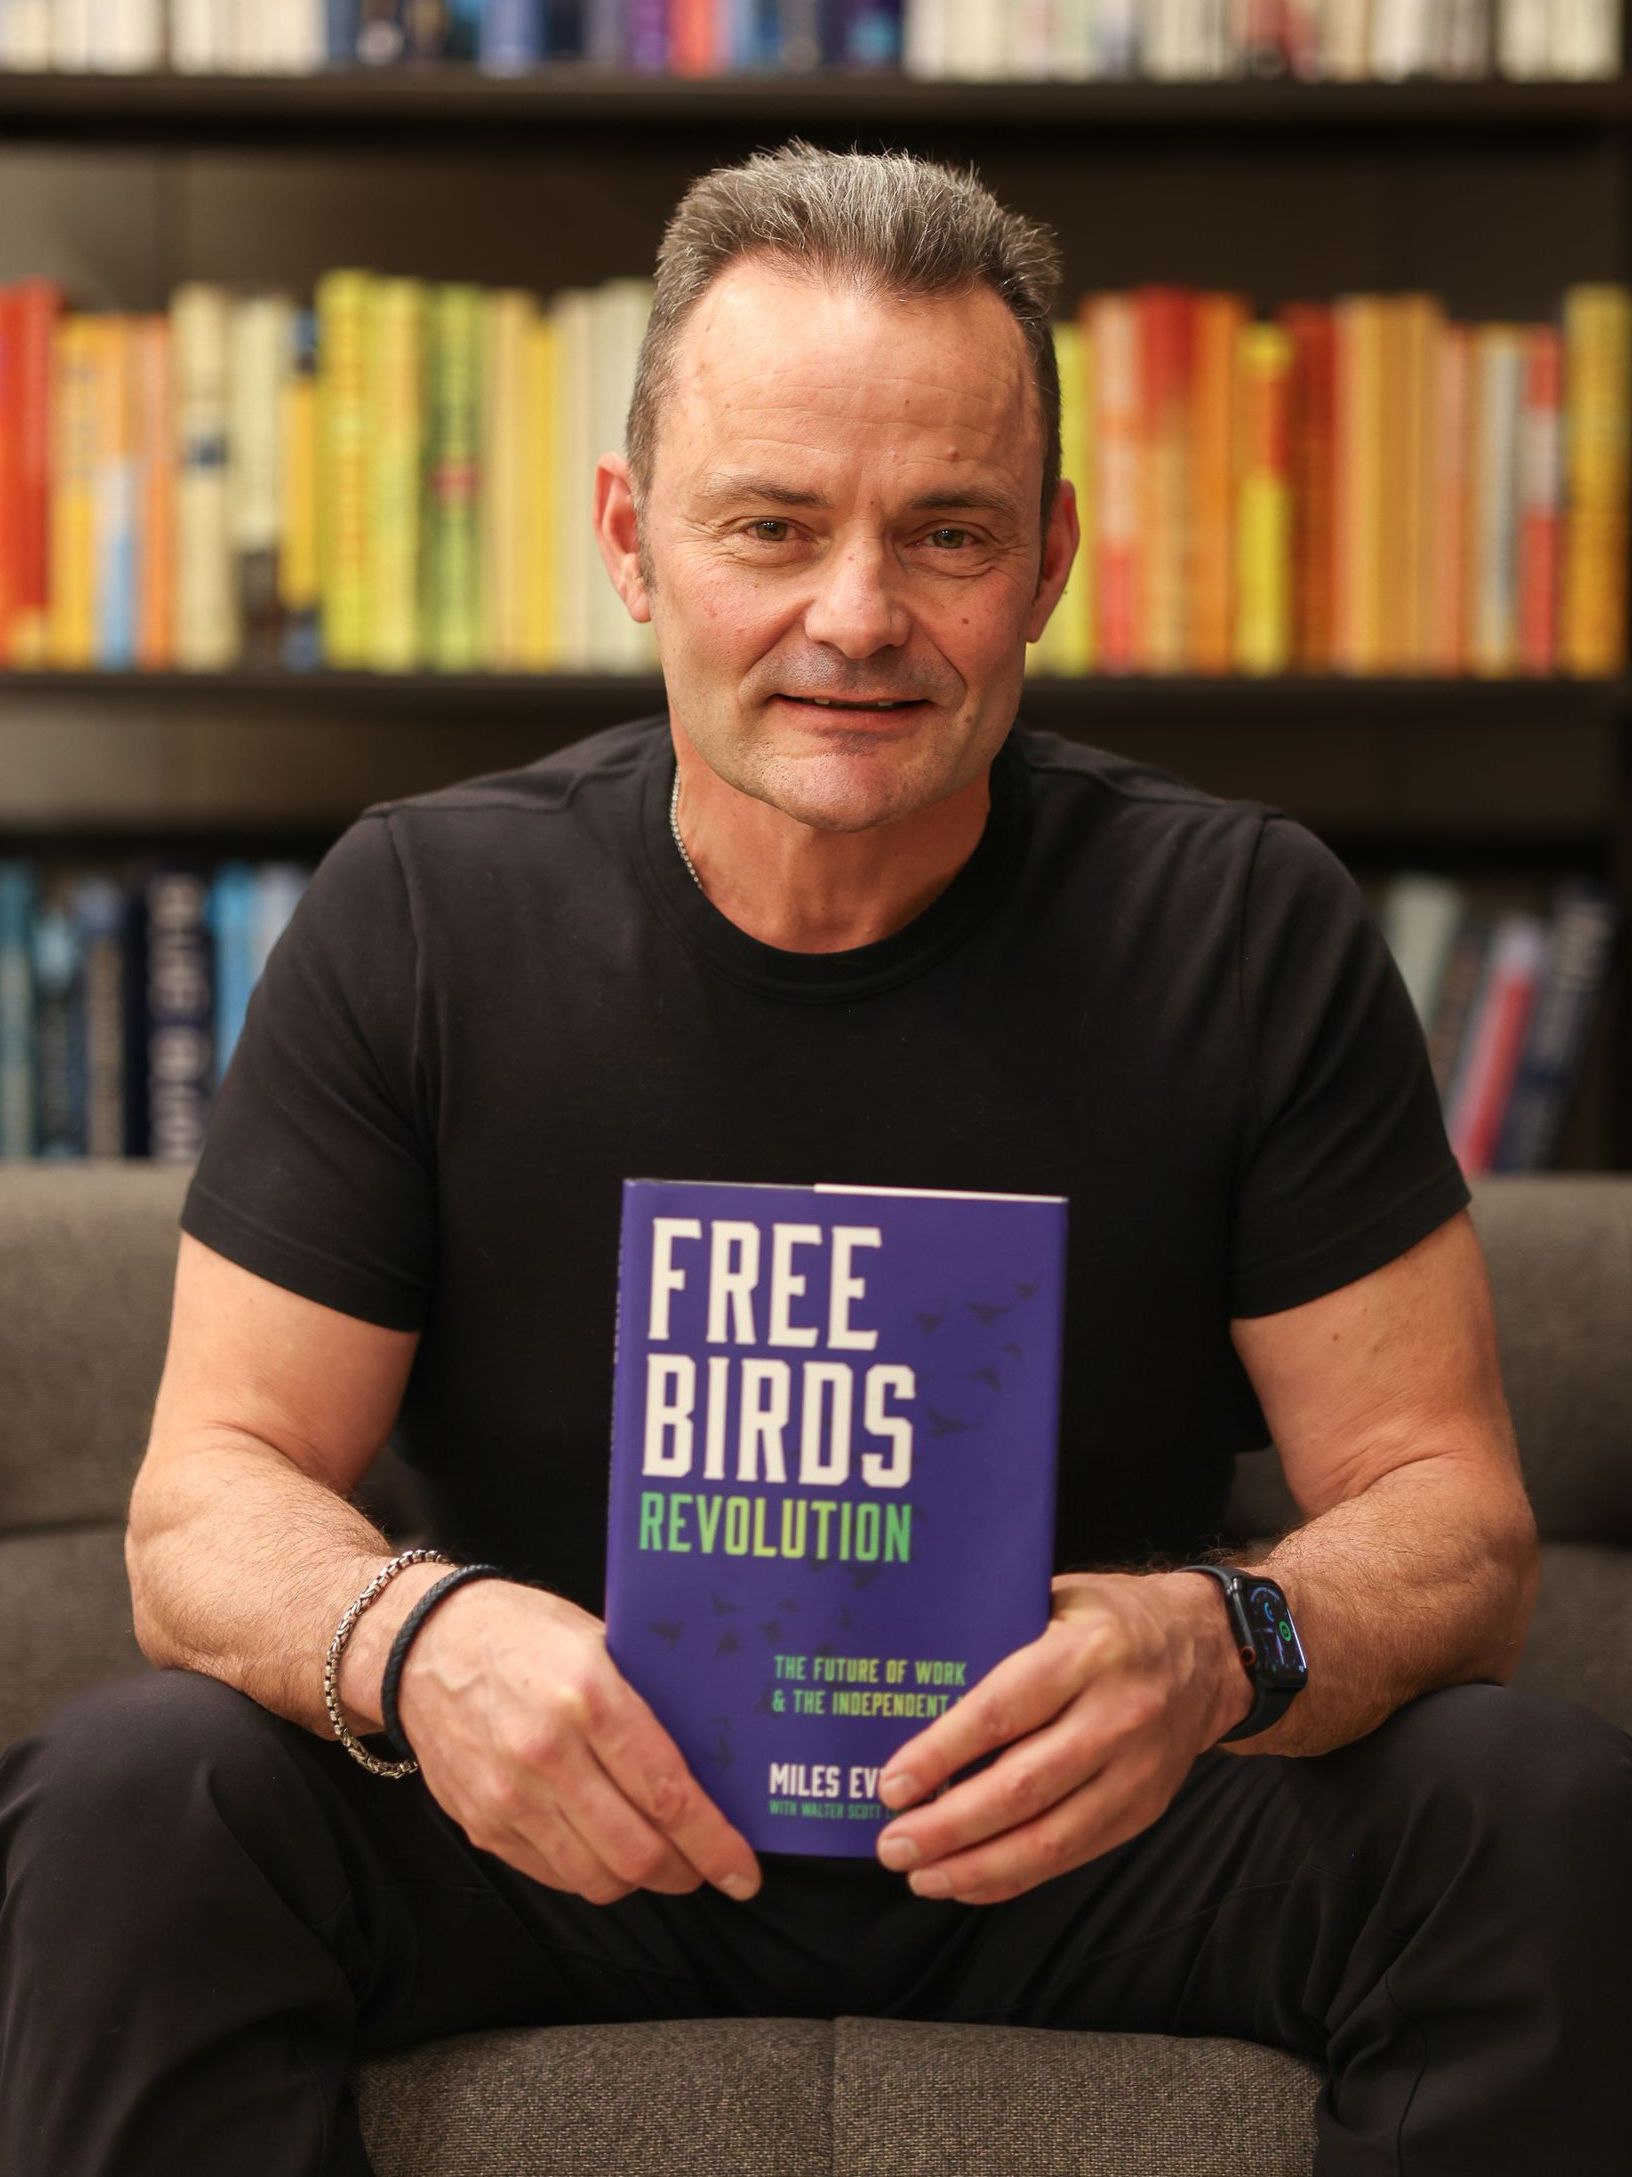
Miles Everson
CEO of MBO Partners and former Global Advisory and Consulting CEO at PwC, Everson has worked with many of the world's largest and most prominent organizations, specializing in executive management. He helps companies balance growth, reduce risk, maximize return, and excel in strategic business priorities.
He is a sought-after public speaker and contributor and has been a case study for success from Harvard Business School.
Everson is a Certified Public Accountant, a member of the American Institute of Certified Public Accountants and Minnesota Society of Certified Public Accountants. He graduated from St. Cloud State University with a B.S. in Accounting.