Bond yields are rising… but not for the reason many investors seem to think.
| From the desk of Miles Everson: Investing has provided many individuals with the opportunity to attain financial independence for decades. That’s why every Wednesday, I talk about this activity in the hopes of helping readers achieve financial independence. Today, we will talk about rising bond yields, and why inflation may not be the cause. Curious? Continue reading below! |
For the past few weeks, the bond market has been the focus of mainstream media coverage. This is because the 10-year Treasury yield is on the rise, and investors are starting to worry. Some worry government spending is getting out of control, inflation is about to take off again, and the bond market is revolting in response. Some people even talk about the return of the so-called “ bond vigilantes .” The popular explanation for rising yields is that investors are punishing Washington. Treasury bonds promise investors a fixed income stream. However, if investors expect inflation to stay high, those future dollars become less valuable. So they may demand a higher return before they're willing to buy Treasurys.
That's what bond investors mean when they say they're “punishing” Washington. The idea is that investors are demanding higher interest rates because they no longer trust the government to keep spending or inflation under control. There's also the fear that the Federal Reserve is “losing its grip.” The Fed can't simply set the 10-year Treasury yield wherever it wants. Long-term rates are determined by investors. So, if the Fed says inflation is under control but investors disagree, the 10-year yield can keep climbing. That sounds like a reasonable explanation for rising yields today, but there's a problem. The data paints a different picture… High Inflation ≠ Rising Bond yields According to Rob Spivey , the Director of Research at Valens Research and Altimetry Financial Research, there’s another explanation for rising treasury yields: “The economy is competing for capital.” Spivey says we gauge investors' inflation expectations over several years using the five-year breakeven inflation rate. This can also compare that with the Cleveland Fed's estimate of five-year inflation expectations. Based on the data, both measures calm right now. The five-year breakeven rate is around 2.2%. The Cleveland Fed's measure is around 2.4%. Both are close to their long-run averages and below the peaks seen in 2022. More importantly, neither has moved meaningfully higher as Treasury yields have risen.
A Treasury yield has two basic pieces: One compensates investors for the inflation they expect over the life of the bond. The other is the return they demand above inflation for tying up their money. So, if inflation expectations barely move while Treasury yields climb, inflation can't explain much of the increase. This can be seen even more clearly by looking at the 10-year yield, excluding inflation. Treasury Inflation-Protected Securities (TIPS) are government bonds that exclude inflation entirely. The 10-year TIPS yield reveals the real return investors demand, but with inflation stripped out. That yield has been climbing steadily.
While it looks like yields are reaching extreme highs, Spivey says we're still around “normal” levels historically, apart from the window where we had near-zero yields after the Great Recession. This means the rise is coming entirely from the real return side, not from inflation fears. According to Spivey, that tells us demand for credit is what's rising. The AI Build-out The real driver of higher rates is competition for capital . You see, some of the biggest companies on Earth are spending unprecedented amounts of capital on the AI infrastructure build-out. Alphabet, Amazon, Oracle, Meta, and their peers are pouring hundreds of billions of dollars into the infrastructure needed to support the AI boom. Microsoft's capital expenditures cost around USD 65 billion in fiscal 2025. The vast majority went to data centers and other AI-related infrastructure. Alphabet spent over USD 90 billion in 2025, up from about USD 52.5 billion the year before. Meta spent roughly USD 70 billion in 2025, while Amazon is expected to spend USD 200 billion this year. Spivey says that's an enormous amount of capital chasing one investment theme. For years, these companies could fund expansion almost entirely from their own cash flow. Their businesses generated so much cash that they rarely needed to issue significant amounts of debt. Now, that’s changing, as even the biggest companies are tapping into the debt markets. Meta has issued multibillion-dollar bonds, including a roughly USD 30 billion offering in 2025. Alphabet has raised billions through debt markets as it finances data-center expansion and other long-term investments. In other words, some of the world's biggest companies are now competing with the U.S. government for investors' money. Debt works like any other market. When everybody wants the same scarce thing, prices rise. In this case, the thing everybody wants is capital, and the price of capital is the interest rate. That's why Treasury yields are rising while inflation expectations remain contained. Companies see enough attractive investment opportunities that they're borrowing at rates that would have seemed steep just a few years ago, all because they believe the returns on AI infrastructure will more than justify the costs. According to Spivey, that's a sign of economic strength, not weakness. The AI infrastructure build-out is still in its early stages, and the companies supplying its physical backbone are sitting at the center of the biggest capital-investment cycle in decades. Hope you’ve found this week’s insights interesting and helpful. Stay tuned for next Wednesday’s The Independent Investor! Markets have once again demonstrated their ability to reward momentum. Stocks that surged in prior months continue to attract capital, reinforcing the belief that winners will keep winning. Learn more about why you shouldn’t get stuck trading eggs in next week’s article! |


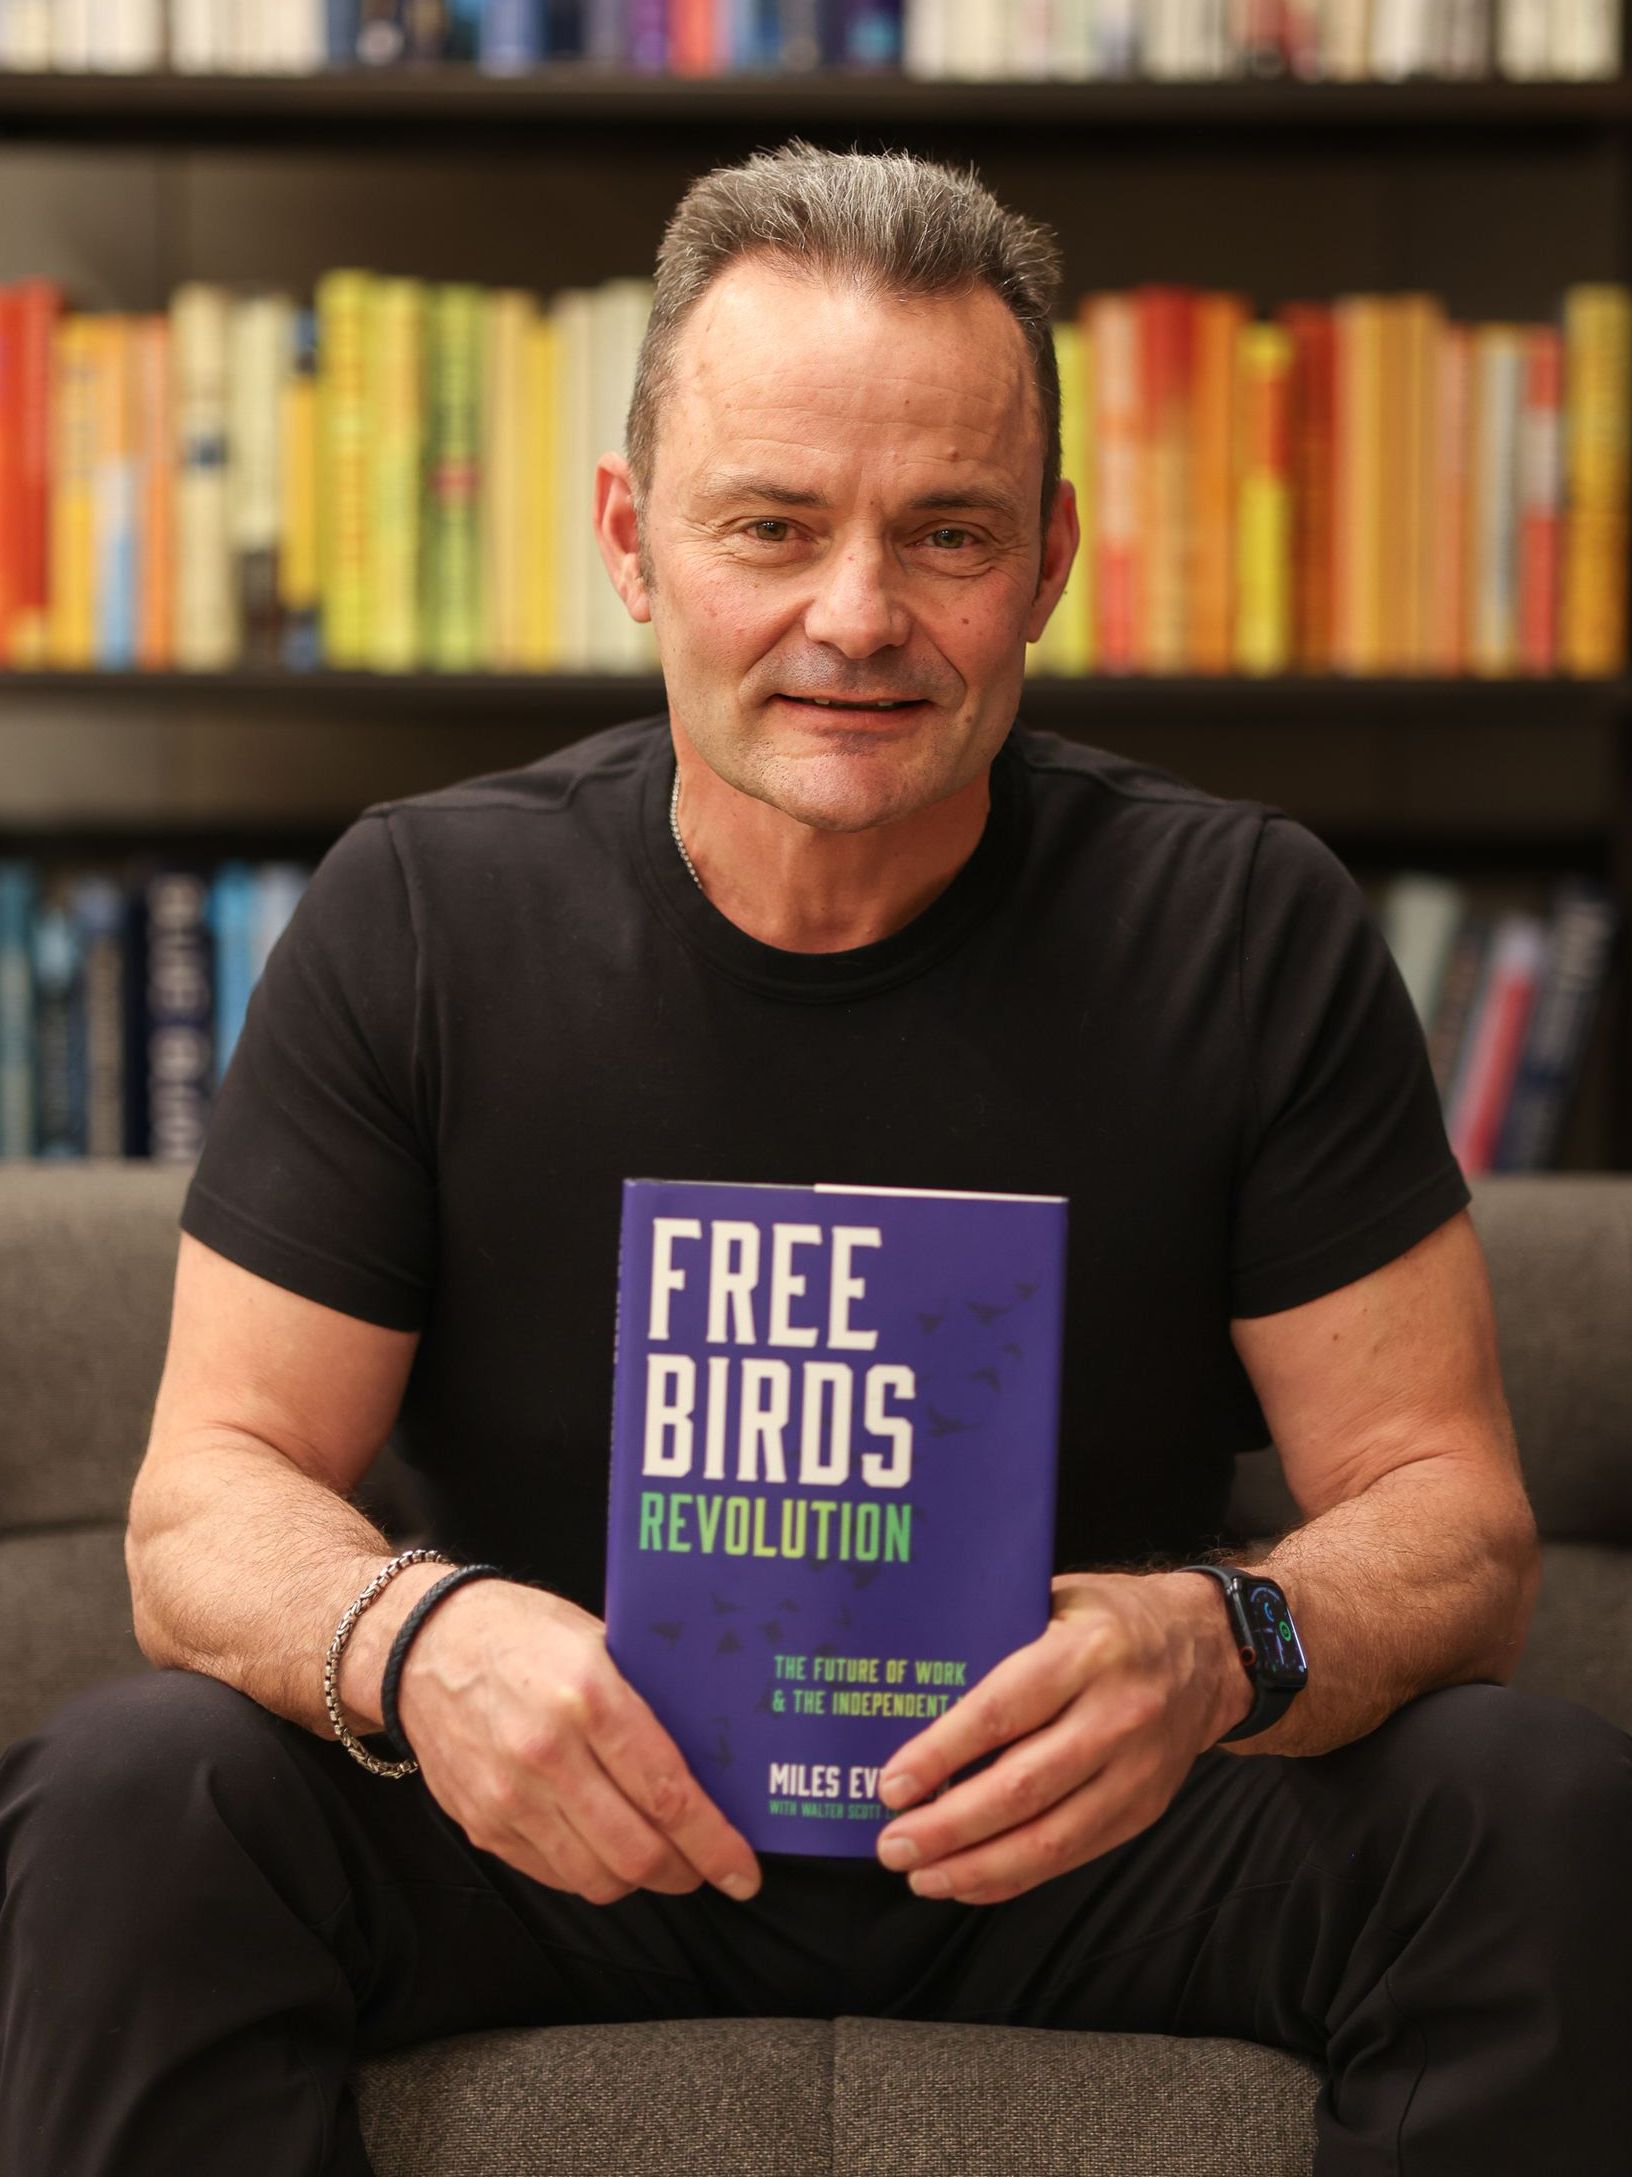
Miles Everson
CEO of MBO Partners and former Global Advisory and Consulting CEO at PwC, Everson has worked with many of the world's largest and most prominent organizations, specializing in executive management. He helps companies balance growth, reduce risk, maximize return, and excel in strategic business priorities.
He is a sought-after public speaker and contributor and has been a case study for success from Harvard Business School.
Everson is a Certified Public Accountant, a member of the American Institute of Certified Public Accountants and Minnesota Society of Certified Public Accountants. He graduated from St. Cloud State University with a B.S. in Accounting.